ASRS and AASB S2 Explained: A Guide to Mandatory Climate Reporting in Australia
20 January 2026
20 January 2026
October 15th 12pm (AEDT)
Australia’s mandatory climate reporting requirements commenced on 1 January 2025 under the Australian Sustainability Reporting Standards (ASRS). At the centre of the regime is AASB S2, the mandatory climate-related disclosure standard that requires eligible organisations to disclose climate-related risks and opportunities through an annual Sustainability Report.
This guide explains ASRS and AASB S2, including who must report, reporting timelines, Scope 3 emissions requirements, assurance obligations and practical steps to prepare.
The Australian Sustainability Reporting Standards (ASRS) are new standards for assessing and disclosing climate-related financial disclosures. This includes information about an entity’s climate and sustainability-related risks and opportunities. The standards are internationally aligned to the International Sustainability Standards Board (ISSB) IFRS standards, to ensure consistent and transparent reporting globally.
The ASRS currently includes two standards – one is mandatory and one is voluntary (at this stage). They are:
Applicable for mandatory climate reporting (integrates IFRS S1 and S2).
“‘This Standard requires an entity to disclose information about climate-related risks and opportunities that could reasonably be expected to affect the entity’s cash flows, its access to finance or cost of capital over the short, medium or long term. For the purposes of this Standard, these risks and opportunities are collectively referred to as ‘climate-related risks and opportunities that could reasonably be expected to affect the entity’s prospects.’ AASB S2 is available here from the AASB website.
This is voluntary for sustainability matters other than climate.
“This Standard requires an entity to disclose information about all sustainability-related risks and opportunities that could reasonably be expected to affect the entity’s cash flows, its access to finance or cost of capital over the short, medium or long term. For the purposes of this Standard, these risks and opportunities are collectively referred to as ‘sustainability-related risks and opportunities that could reasonably be expected to affect the entity’s prospects.’
More information on AASB S1 is available here from the AASB website.
As AASB S2 underpins mandatory climate reporting, it is the one business leaders are focusing their immediate attention on.
AASB S2 requires reporting entities to assess and disclose information about their climate-related risks and opportunities, with a focus on improving consistency, comparability and transparency of reported information. Some Australian businesses are also considering AASB S1 to enhance broader sustainability-related disclosures and to prepare for future mandatory standards on nature and other topics.
The Australian Accounting Standards Board (AASB) developed the ASRS based on the International Financial Reporting Standards (IFRS) S1 and S2, issued by the International Sustainability Standards Board (ISSB), which set a comprehensive global baseline for sustainability-related financial disclosures.
The IFRS sustainability standards are being implemented by many jurisdictions globally and build on the work of the previous reporting guidance from the Taskforce for Climate-related Financial Disclosures (TCFD).
Download exclusive insights from our ASRS Executive workshops on the learnings from the first year of reporting
No. In Australia, AASB S2 includes relevant provisions from AASB S1 / IFRS S1 for the purpose of climate-related disclosures, avoiding the need to consider AASB S1 separately. You may wish to consider AASB S1 for nature and other sustainability-related disclosures.
One of the first steps is understanding whether your organisation is in scope of Australia’s mandatory climate reporting requirements, and when those requirements apply. Organisations that are not yet required to report may also choose to voluntarily align with ASRS and AASB S2.
Your organisation or financial product may be required to report if it publishes financial statements under Chapter 2M of the Corporations Act, including:
Reporting is phased in based on a range of entity sizes and emissions criteria. To understand if your organisation falls under Group 1, 2 or 3, see the criteria below:
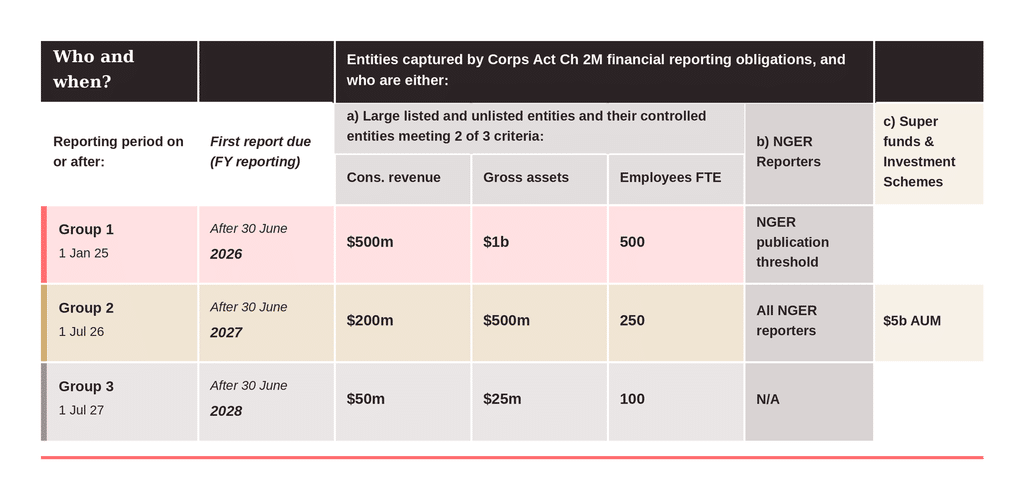
Under the new mandatory climate reporting rules in Australia, companies must prepare an annual ‘Sustainability Report’ which forms part of annual reporting, alongside financial statements.
The timing of publication must be consistent with the requirements under the Corporations Act for corporate reporting. More on that below under timelines.
Under the Corporations Act, the Sustainability Report consists of:
Climate Statements
Climate Statements must include information on climate-related risks and opportunities in line with AASB S2. This requires information including on:
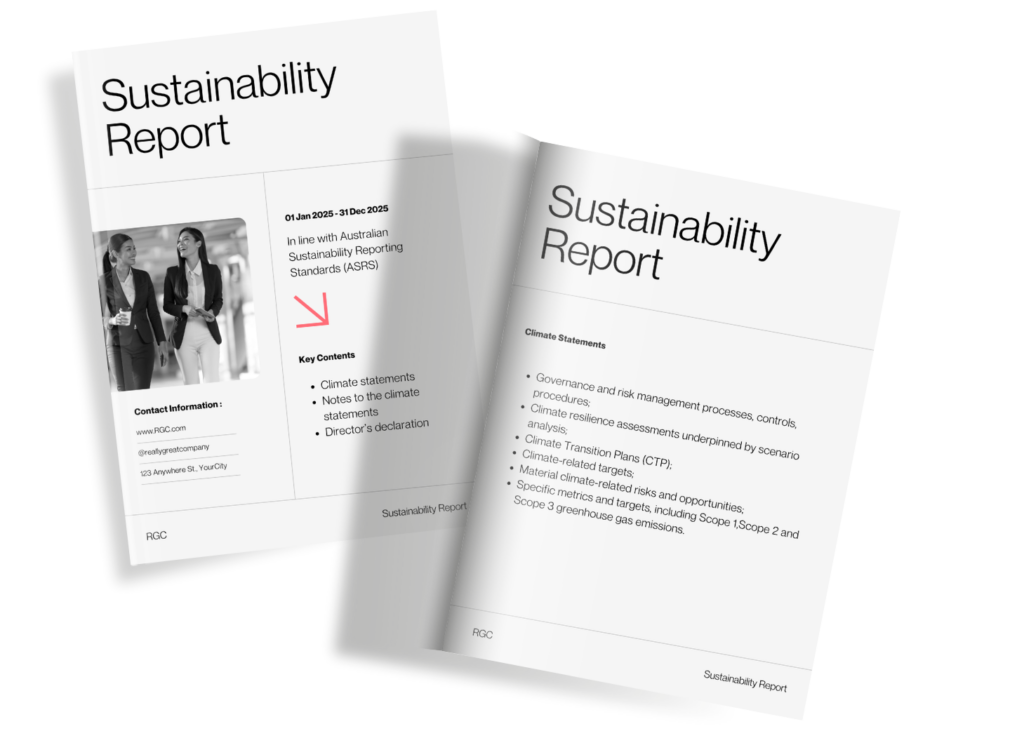
The directors’ declaration is a critical part of the Sustainability Report. This is similar but distinct from the director’s declaration for financial statements.
The declaration confirms that the climate-related disclosures (i.e. the climate statement and notes) comply with the Corporations Act and AASB S2.
Reporting commences from 1 January 2025 and applies to your first full reporting period on or after that date.
The reporting period for Sustainability Reports must align with your financial reporting.
Report timing aligns with your first full financial reporting period on or after 1 January 2025.
For example, if you complete financial reporting for the period 1 July to 30 June, your first reporting period is 1 July 2025 to 30 June 2026 (FY26).
Commonwealth public sector entities will also be captured by new Commonwealth Climate Disclosure requirements, tailored for the public sector. Read here for more information on Public Vs Private Climate-related Financial Regulations in Australia.
ASIC provide helpful information on their website. Broadly, ‘Reporting entities must lodge their sustainability report and the auditor’s report on the sustainability report with ASIC:
see s319(3) and s1232(1) of the Corporations Act.’
For more information on timelines for varying FY periods and how to lodge the Sustainability Report for ASRS AASB S2 see ASIC’s Sustainability Reporting Information page.
Generally, yes. An overseas parent’s climate report does not automatically satisfy an Australian subsidiary’s reporting obligations. Where an Australian entity falls within the scope of the mandatory climate reporting regime, it will generally need to prepare disclosures in accordance with the Australian Sustainability Reporting Standards (ASRS). Companies should review their specific circumstances and any available relief provisions, as reporting obligations depend on the entity’s structure and regulatory requirements. ASIC has provided guidance on this issue in Regulatory Guide 280 – RG 280.44.
ASRS and AASB S2 allow for a 1-year relief for reporting Scope 3 emissions (which cover indirect emissions related to your organisation’s value chain and financing or investment activities). This means reporting Scope 3 emissions will be mandatory from your second reporting period. For group 1 entities, you should be putting a serious focus on your scope 3, full value chain inventories in 2026.
For a deep dive into Scope 3 emissions under ASRS , read our guide – How To Report Scope 3 Emissions Under ASRS – AASB S2 | Australia
You can also watch our webinar recording on Scope 3 emissions for ASRS – ‘A Closer Look at Material Scope 3 Emissions: How Deep to Dive?’ here.
The AASB issued AASB S2025-1 Amendments to Greenhouse Gas Emissions Disclosures in December 2025, updating AASB S2 Climate-related Disclosures for annual periods starting on or after 1 January 2027. These amendments align AASB S2 with targeted changes made by the International Sustainability Standards Board and clarify key greenhouse gas disclosure requirements. They make it clear that entities may limit Scope 3 Category 15 emissions reporting to financed emissions, provide relief on how financed emissions are classified by industry, and allow flexibility on using alternative GHG accounting methods or jurisdictional measurement approaches where required. More information on financed emissions.
Are there penalties for non-compliance with ASRS and AASB S2?
The non-compliance penalties under ASRS and AASB S2 closely mirror financial reporting penalties under the Corporations Act.
As the regulator, ASIC has stated it recognises there will be a period of transition as industry builds its capabilities and implements the organisational changes required to comply with these mandatory climate-related reporting requirements. Accordingly, they will take ‘a pragmatic and proportionate approach to supervision and enforcement as industry adjusts to the new requirements.’
In March 2025 ASIC released its regulatory guidance, Regulatory Guide 280. “It explains how ASIC will exercise specific powers under legislation (primarily
the Corporations Act), how ASIC interprets the law and the principles
underlying ASIC’s approach. It also provides practical guidance to entities
about complying with their sustainability reporting obligations.” ASIC.
In line with non-compliance penalties for financial reporting, directors may face personal liability for misleading statements in Sustainability Reports due to a lack of due diligence. False or misleading climate statements could result in penalties up to $15 million or 10% of annual turnover, with directors personally liable.
The smallest company size thresholds (i.e., in Group 3) match those for large proprietary companies under the Corporations Act, meaning most SMEs are excluded.
The Legislation allows the Minister to lower these thresholds in the future, potentially including more entities.
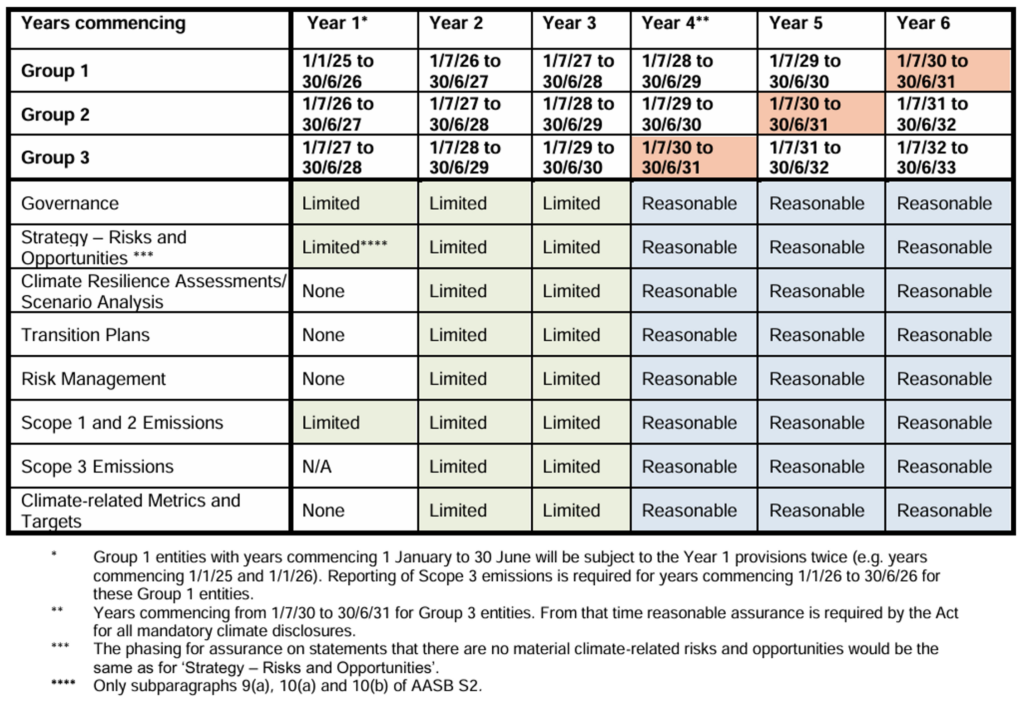
The AUASB released ASSA 5000 and ASSA 5010 in January 2025 as Australia’s first sustainability assurance standards.
ASSA 5000 sets the foundational requirements for how assurance over sustainability information must be conducted across all topics and frameworks, while ASSA 5010 defines which disclosures must be reviewed or audited and the timeline for doing so. Together, they create a structured pathway that not only supports credible assurance but also acts as a practical guide for organisations preparing their disclosures.
Organisations that align early with the expectations in ASSA 5000 and the staged approach in ASSA 5010, will strengthen internal systems, anticipate assurance needs and build reporting processes to ensure compliance.
From 1 July 2030, climate disclosures will move to full reasonable assurance under the Corporations Act. This shift means organisations will need an audit opinion that provides positive assurance that their climate information complies with legislative requirements and the applicable Australian Sustainability Reporting Standards. See below for ASRS assurance timelines from AUASB.
The need for standardised, mandated reporting is being recognised globally, with countries around the world implementing climate-related disclosure requirements similar to Australia.
For the last decade, Australian companies have been reporting on their climate-related sustainability efforts using a range of global and voluntary standards. This lack of unified structure poses challenges for stakeholders in understanding and comparing a company’s approach, objectives and prospects towards climate and sustainability, particularly in the context of risk management, targets and transition plans.
Investors now want to understand clearly how companies incorporate sustainability considerations into their strategic decision-making, risk management, and financial statements. They want to know how a company’s sustainability-related risk and opportunities align with its strategy and business model and, ultimately, its prospects for creating long-term value.
From submissions to the consultation, it is clear that many business leaders view the ASRS as a crucial step toward improving transparency and accountability in sustainability reporting. They see it as both a compliance requirement and an opportunity to enhance governance, drive innovation, and meet market expectations. Leaders also welcome the government’s commitment to positioning Australia as a global sustainability leader by promoting sustainable finance.
Key benefits of climate-related reporting in line with ASRS and AASB S2 and AASB S1 include:
Here are some key questions your organisation should be asking itself to begin preparing for compliance with ASRS and AASB S2.
The Australian Accounting Standards Board (AASB) developed the Australian Sustainability Reporting Standards (ASRS) based on the International Sustainability Standards Board (ISSB) framework, including IFRS S1 and IFRS S2. The standards build on the recommendations of the Task Force on Climate-related Financial Disclosures (TCFD) and align Australia with a broader global trend towards mandatory sustainability and climate-related reporting.
Many jurisdictions are implementing similar requirements, including the European Union, Singapore and the Philippines. Learn more about global developments in our guide to the latest changes in ISSB standards.
Key steps organisations should take now who are preparing for reporting include:
Learn how we provided The Sussan Group with expert support to prepare for its inaugural climate disclosures under ASRS and reporting to AASB S2 and strengthen its emissions reporting processes. Link to case study.
Anthesis Intelligence – digital tools for preparing for ASRS and AASB S2, can support your gap analysis, scope 3 inventory, reporting and more from an audit-ready perspective. Learn more and reach out for a demo.
Anthesis supports organisations with ASRS and AASB S2 readiness, gap assessments, climate disclosures, Scope 3 reporting and assurance preparation.
Anthesis experts can guide you through the full process of reporting to the Australian sustainability standards or assist with particular elements of reporting, such as analysing your climate-related risks and opportunities, scenario analysis, Scope 3 reporting and climate transition planning. We can guide you on how to integrate outcomes into strategic plans and risk management processes, ensuring you’re prepared for compliance. Our digital solution within Anthesis intelligence, is designed to align with ASRS disclosures, providing a streamlined solution for data collection and management. It ensures transparency, data integrity and rigour, supporting your reporting processes and assurance requirements.
As technical experts and trusted advisors to some of the world’s most well-known companies for over a decade, and have helped hundreds of clients with reporting to Frameworks and Standards. We’re here to help you through this new era of reporting.


See more insights below and check out our events page to learn from our experts in our 6 Part Flash Webinar Series dedicated to navigating the ASRS AASB S2 standards.
Original post published October 2024, last updated January 2026.
We’re here to help you navigate the complexity of the new disclosures. Call us for a chat on +61 3 7035 1740 or reach out to our experts via email or this form.


